
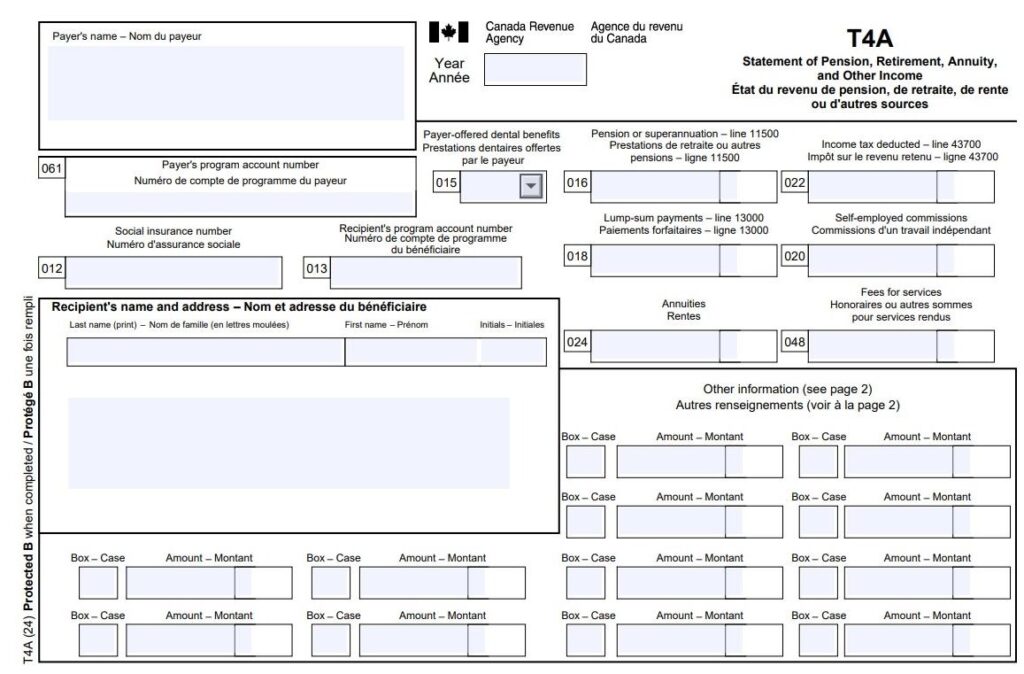
A T4A is shorthand for the “Statement of Pension, Retirement, Annuity, and Other Income.” It’s a mouthful, but for most small businesses it comes down to one thing: it’s how you report what you paid your independent contractors.
T4As are more commonly associated with contractor relationships, where no employment contract exists. However, they can also be issued to employees, retired workers and shareholders or directors to account for other types of income as well. Here is a list of exceptions.
Note: Construction is its own world. Payments to subcontractors for construction services are reported on a T5018 slip, not a T4A, so they aren’t covered in this article.
Issuing T4As for contractors
As a small business employer, the most common reason you’d issue a T4A is to provide year-end documentation to an independent contractor that indicates how much you paid them. They’ll use this form to file their self-employment taxes and CRA will use the T4A information you filed, to cross-check the two.
The golden rule: If you pay a contractor $500 or more for their services (not including GST/HST) within a calendar year, you must issue a T4A.
Classification risk: CRA may review the contractor relationship. If the result of the audit decides the worker should have been an employee, you could be held liable for unpaid CPP and EI contributions, plus interest.
If you aren’t sure how to distinguish the relationship between an employee and a contractor, check out our guide: Contractor vs. Employee in Canada: What’s the Difference?
Key T4A deadlines and filing rules
T4A season lands at the same time as T4s, so it’s easy for contractor slips to slip down the to-do list. Here’s what to keep on your radar for your business, or for every client file you manage.
- Deadline: T4A slips are due to the CRA and to your contractors by the last day of February following the calendar year they cover. If that day falls on a weekend or public holiday, you have until the next business day. Either way, it’s the same deadline as your T4s, so plan to tackle both together.
- Electronic filing: If you’re filing more than 5 T4A slips for the year, you must file electronically. The CRA offers Web Forms and internet file transfer, or you can use payroll software that files for you. Filing on paper when you’re required to file electronically can mean a separate penalty, so check the slip count for each payroll account before you file.
- Currency: Report all amounts in Canadian dollars, even if you paid a contractor in US dollars or another currency. The CRA generally expects you to use the Bank of Canada exchange rate for the day the amount was paid.
- Penalties: Late slips can cost you. The CRA’s late-filing penalty starts at $100 and goes up with the number of slips and how many days late they are. See When to file for current penalty details.
Pro tip: Don’t wait until February to chase down contractor details. Collect each contractor’s SIN or business number, legal name and mailing address when you first engage them. Your future self, buried in year-end slips, will thank you.
Understanding the T4A boxes
Here are the boxes small businesses use most often. For the full list, see the CRA’s T4A slip – Information for payers.
| Box | What it reports |
|---|---|
Payer’s and recipient’s information |
On a contractor T4A, your business is the payer and the contractor is the recipient. Enter your business’s name and address, then the contractor’s name and address. For an individual, enter last name, first name and initial. For a business, enter its business name. |
Box 012 — Recipient’s SIN |
The contractor’s Social Insurance Number, if they’re an individual. If they haven’t provided one, enter nine zeros (the slip is still due). For a partnership or corporation, leave this box blank and use Box 013 instead. |
Box 013 — Recipient’s program account number |
If the contractor is a business (including a sole proprietor, partnership or corporation), enter their CRA business number (for example, 123456789RT0001). |
Box 015 — Payer-offered dental benefits |
Supports the Canadian Dental Care Plan (CDCP). Use codes 1–5 to report whether the recipient, or any of their family members, had access to dental coverage of any kind from you as of December 31, whether or not they used it. Required when you report an amount in Box 016. Otherwise optional. See the CRA’s Box 015 guidance. |
Box 016 — Pension or superannuation |
Used in specific situations, such as payments from registered or unregistered pension plans, certain disability and veterans’ benefits, employee benefit plans or retirement compensation arrangements. Rarely used for contractors. |
Box 018 — Lump-sum payments |
Specific lump-sum amounts, such as certain pension plan payments. Check the CRA’s list of qualifying circumstances. |
Box 020 — Self-employed commissions |
Commissions you paid to an independent agent. Don’t include GST/HST or provincial sales tax. |
Box 022 — Income tax deducted |
Leave this box blank unless you actually deducted income tax. Independent contractors are typically responsible for their own taxes. |
Box 048 — Fees for services |
The box most small businesses use. Enter the total fees for services you paid the contractor during the calendar year. Don’t include GST/HST or PST. |
Box 061 — Payer’s program account number |
Your business’s 15-character payroll account number (for example, 123456789RP0001). It goes on the CRA copy only, not the recipient’s copy. |
Bottom of T4A — Other information area
The second most common place for small business employers to document amounts paid to contractors is using Code 28 — Other income. Here’s a full list of the income codes for a T4A.
If you have more than 12 codes for the same contractor, create a second T4A. The only thing you have to repeat is your business’s and the contractor’s identifying information.
Other reasons a T4A might be issued:
A T4A may also be issued when you pay any of the following types of income: (In the case of these types of incomes, you issue the T4A because you deducted CPP/QPP and/or EI from the amounts.)
General guidelines for completing a T4A
The following links can help you find more detailed info on T4As:
- T4A Information for Payers
- Guide to Filling Out the T4A Slip
- Full List of T4A Boxes & Codes
- How to Amend or Fix T4A Slips
What is a T4A Summary
If the T4A slips are the chapters of your contractor story, the T4A Summary (T4ASUM) is the table of contents. It reports the totals of all the information you’ve provided on the individual T4A slips for the calendar year.
Key requirements for the T4A Summary
- One per account: You must fill out a separate T4A Summary for each of your payroll program accounts (those 15-character numbers ending in RP0001, RP0002, etc.).
- Match your slips: The totals on your summary must exactly match the sum of all the boxes on your individual T4A slips.
- Report in CAD: Even if you paid a contractor in another currency, all amounts on the summary must be converted to and reported in Canadian dollars.
- Don’t file “nil” returns: If you have no amounts to report and didn’t issue any T4A slips, you don’t need to send a summary to the CRA.
Keep it simple with Wagepoint
Contractor pay shouldn’t be a headache. With Wagepoint, you can pay your contractors right alongside your regular employees. We’ll track the payments throughout the year and generate the T4As for you when February rolls around.
Standard legal disclaimers
Someone’s gotta make the lawyers happy. (Yep, there’s something out there that’s even more painful than payroll, childbirth or gardening documentary marathons.)
The advice we share on our blog is intended to be informational. It does not replace the expertise of accredited business professionals or the responsibility of the business owner to ensure compliance.
To qualify for complimentary T4s with Wagepoint (included as part of your standard fees) — a business must run a minimum of two payrolls in the current calendar year.
Remittance and reporting capabilities within Wagepoint vary by location.