As a Canadian small business owner, staying compliant with the Canada Revenue Agency (CRA) is a crucial part of your role, and your employees rely on you to get it right. That includes understanding CPP2, the second phase of the Canada Pension Plan (CPP) enhancement.
Much like the endless follow-ups to Scream, you might be wondering: does CPP really need a sequel? With multiple names like “CPP enhancement” and “second additional CPP,” plus a host of guidelines to learn, understanding this update can definitely feel like a scary movie.
But unlike questionable movie sequels, CPP2 deserves your attention. It directly affects your payroll and adds responsibilities for you as an employer.
So let’s untangle the jargon and look at how CPP2 affects your business, your employees and your CRA compliance.
Second additional Canada Pension Plan contribution (CPP2)
CPP2 is the second phase of the CPP enhancement, designed to improve retirement security for Canadians. Since 2024, workers who earn above a certain threshold also contribute to the program on earnings between a first and second earnings ceiling (more on that below).
The enhancement responds to longer life expectancies and fewer Canadians having workplace pension plans. Think of it as adding an extra layer to an employee’s retirement safety net.
Just like regular CPP contributions, employers and employees contribute equally to CPP2. For Canadian small business owners, this means slightly higher costs to account for. It also supports your team’s financial future and helps them retire with greater peace of mind.
Understanding CPP and CPP2 contributions
To fully understand how CPP2 affects your payroll, it’s important to first get familiar with the different types of CPP contributions. Here’s a breakdown of how the current system works.
CPP base contributions
This is the original CPP you may already be familiar with. Employees generally contribute if they’re between 18 and 65, work in Canada outside of Québec, and earn more than the basic exemption amount. Employers match employee contributions dollar for dollar. Please review CRA’s CPP contribution rates, maximums and exemptions annually as they change.
Employees aged 65 to 70 who receive a CPP retirement pension must keep contributing unless they elect to stop by giving you a completed Form CPT30. The election takes effect on the first day of the month after you receive the form.
CPP first additional contributions
First additional contributions were introduced in 2019. They apply to the same earnings as base CPP, up to the Year’s Maximum Pensionable Earnings (YMPE), also called the first earnings ceiling.
Base and first additional contributions are calculated together as a single CPP deduction on the paycheque and reported together in Box 16 of the T4. Employers match these contributions as well.
CPP second additional contributions (CPP2)
Introduced in January 2024, CPP2 applies to earnings above the YMPE and up to the Year’s Additional Maximum Pensionable Earnings (YAMPE), or second earnings ceiling. Employers match these contributions too.
In short, CPP2 doesn’t replace the original CPP. It builds on top of it. Base, first additional and CPP2 contributions all count toward an employee’s CPP retirement pension. It’s like upgrading to a deluxe package: better perks at a slightly higher cost.
Employers in Québec: Employees in Québec contribute to the Québec Pension Plan (QPP), including QPP2, instead of the CPP. Visit Revenu Québec for QPP rules and rates.
How CPP earnings ceilings change each year
Now that you understand the building blocks of CPP, let’s look at how the earnings ceilings change annually.
Most years, both earnings ceilings (the YMPE and the YAMPE) go up. They’re indexed to wage growth so the CPP keeps pace with what Canadians earn. When the ceilings rise, employees with higher earnings contribute on more of their pay, and your matching contributions go up with them. The CRA typically announces the next year’s figures every November, so it’s a good time to review your payroll budget.
For the current year’s ceilings, rates and maximums, check the CRA’s CPP contribution rates, maximums and exemptions page.
Here’s an example of previous years.
2025
- CPP YMPE= $71,300 (First earnings ceiling)
- CPP2 YAMPE = $81,200 (Second earnings ceiling)
- This means that CPP2 contributions are calculated on earnings between $71,300 and $81,200
2026
- CPP YMPE= $74,600 (First earnings ceiling)
- CPP2 YAMPE = $85,000 (Second earnings ceiling)
- This means that CPP2 contributions are calculated on earnings between $74,600 and $85,000
How CPP2 contributions are calculated
There are three thresholds that determine which CPP contributions apply to an employee’s earnings:
- Basic exemption amount: no CPP is deducted on earnings up to this amount.
- First earnings ceiling (YMPE): base and first additional CPP apply to earnings between the basic exemption and the YMPE.
- Second earnings ceiling (YAMPE): CPP2 applies to earnings between the YMPE and the YAMPE.
The basic exemption applies only to base and first additional CPP. CPP2 has no exemption of its own. It starts as soon as an employee’s earnings pass the first earnings ceiling.
Here’s how the CPP2 calculation works:
- CPP2 pensionable earnings: the second earnings ceiling (YAMPE) minus the first earnings ceiling (YMPE).
- Employee maximum contribution: CPP2 pensionable earnings × the CPP2 rate.
- Employer contribution: matches the employee amount.
- Self-employed maximum contribution: CPP2 pensionable earnings × double the CPP2 rate, since self-employed individuals pay both portions.
If an employee earns more than the first ceiling, they pay CPP2 only on the part of their earnings above the first ceiling. Once their earnings reach the top of the second ceiling, they’ve paid the maximum CPP2 contribution for the year, and CPP2 deductions stop.
Employer checklist: staying compliant with CPP2
As a small business owner, you have some important CPP2 responsibilities in your payroll process. Here are the steps to follow.
Budget for matching contributions
- Earnings ceilings usually rise each year, so your matching contributions for higher earners may go up too. Check the new figures each fall and build them into your financial planning.
- If you’re self-employed, you’ll cover both the employee and employer portions. It might seem like a lot now, but future you will be high-fiving for those contributions.
Make sure your payroll system is up to date
Check that your payroll system is using the current year’s figures and handles:
- Deducting the correct contributions from employee paycheques.
- Matching employee contributions correctly, including CPP2.
- Remitting both the employee deductions and your matching employer contributions to the CRA.
- Stopping each type of deduction once an employee reaches its annual maximum.
If you use Wagepoint’s online payroll software, Wagepoint automatically calculates CPP and CPP2 contributions for each employee, so you don’t have to work out the ceilings yourself.
Communicate with employees
- Be proactive. Let employees know how CPP2 works so they aren’t caught off guard by changes in their net pay.
- Explain when CPP and CPP2 contributions start and stop and how it resets annually.
- Share resources to help employees understand the changes. Transparency makes all the difference.
How does CPP2 affect payroll year-end?
Year-end is your chance to make sure everything is balanced and compliant. As an employer, you’ll confirm that the correct CPP and CPP2 contributions were deducted from each employee’s pay throughout the year. That means reviewing and balancing year-end totals before you file T4 slips.
Recording CPP2 on T4s
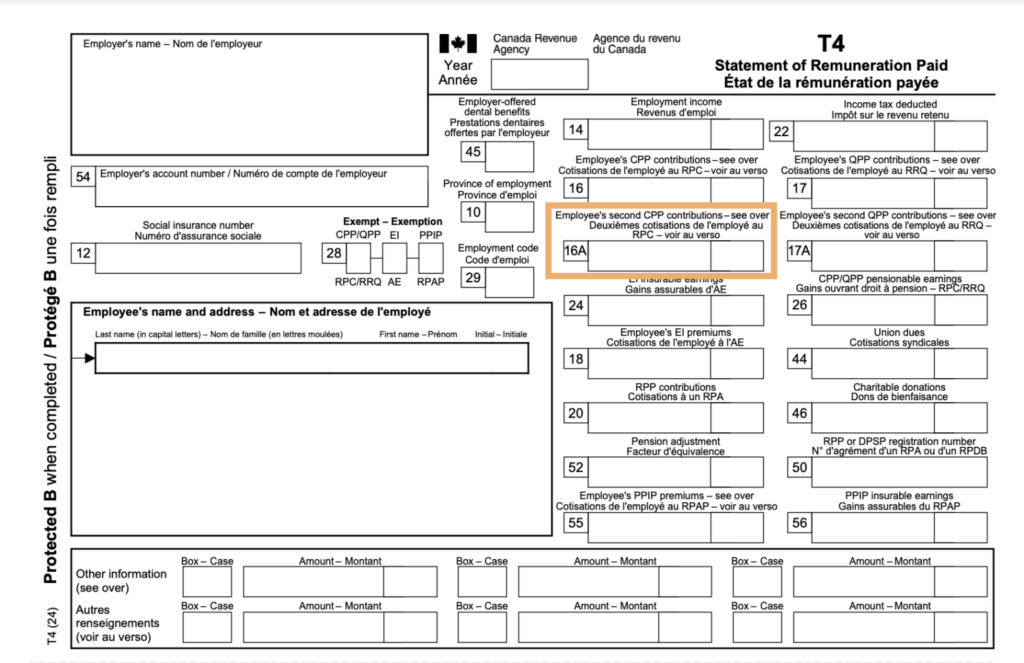
On your employees’ T4 slips, CPP2 contributions are reported separately from CPP contributions:
- Box 16: Reports CPP contributions.
- Box 16A: Reports CPP2 contributions. If no CPP2 was deducted, leave Box 16A blank.
- Box 26: Report CPP pensionable earnings, up to the second earnings ceiling (YAMPE).
Building a better retirement for your team
As a small business owner, you’re the unsung hero shaping your employees’ financial futures. Keeping up with CPP and CPP2 might take a bit more work now, but the payoff is worth it: a more secure retirement for your team. By staying compliant and keeping them in the loop, you’re helping make sure they’re financially secure long after the release of Scream 47: Retirement Scream-along.